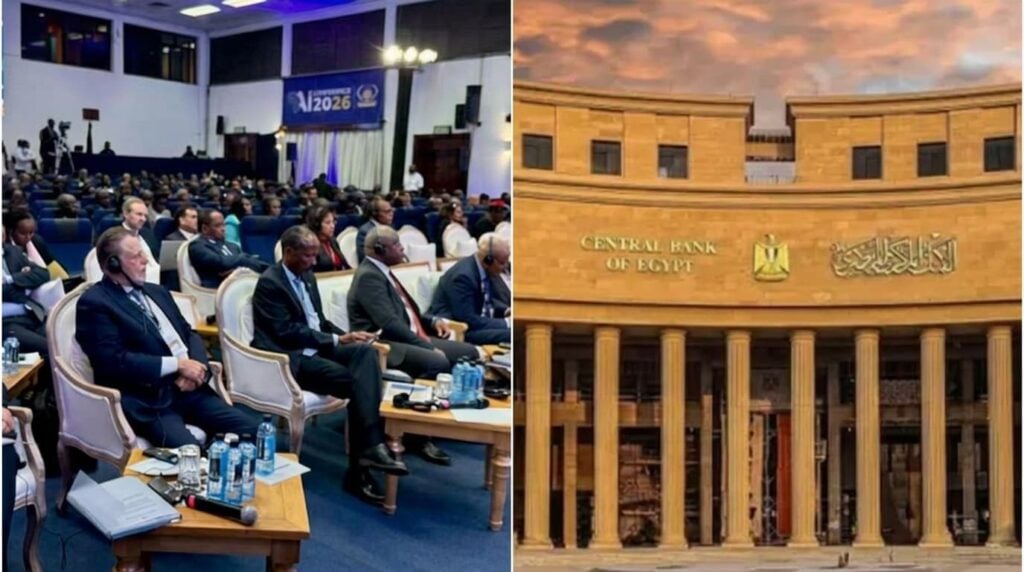
The growing use of artificial intelligence in central banking has come under scrutiny at the 48th annual meetings of the Association of African Central Banks (AACB) in Nairobi, with Central Bank of Egypt Governor Hassan Abdalla highlighting both the potential benefits and risks of adopting the technology across financial systems.
The annual meetings are being held in Nairobi from 13 to 18 September and are hosted by the Central Bank of Kenya, which is marking its 60th anniversary. The gathering has brought together central bank governors from more than 40 African countries, alongside financial experts, regulators, representatives of financial institutions and international organisations.
An AI-focused high-level conference is being held alongside the annual meetings to consider how central banks can make practical use of the technology while ensuring that its deployment remains secure and responsible. The discussions come as financial authorities face growing volumes of data and increasingly complex demands for timely economic and financial analysis.
Three main areas have dominated the AI discussions: its potential role in monetary policy and financial stability; applications in banking supervision and financial integrity; and the use of AI in governance and risk management.
Participants have also examined how AI could support the day-to-day work of central banks. Potential applications include analysing large and diverse datasets, assisting with economic forecasts, processing documents, managing institutional knowledge and preparing reports.
For central banks, the ability to process large amounts of information efficiently can be particularly relevant. Economic and financial institutions routinely work with extensive datasets and documents, while monetary and supervisory decisions require information to be assessed from multiple sources. AI tools could assist with these processes, although the discussions in Nairobi also emphasised the need for appropriate safeguards and responsible deployment.
The readiness of individual African countries to adopt AI was another key issue. Countries vary considerably in their digital infrastructure, technical expertise, data systems and institutional capacity. These differences can affect the pace at which central banks introduce AI and the extent to which they can integrate it into existing systems.
Regional cooperation was therefore identified as an important element in developing common approaches to responsible AI use. Sharing experience and building compatible frameworks could help African financial authorities address common technological and regulatory challenges while strengthening their capacity to manage emerging risks.
Abdalla’s participation comes as the Central Bank of Egypt continues to expand cooperation and capacity-building with other African central banks in areas including digital transformation, financial technology, data governance and cybersecurity.
The Egyptian central bank has shared expertise with institutions including the Bank of Ghana and the Bank of Tanzania. Its cooperation with these institutions has covered AI and digital transformation, as well as crisis management, banking supervision, payment systems and cash management.
Egypt is also seeking to strengthen its broader AI infrastructure. The country is looking for investment in AI data centres while expanding cloud-computing and other digital infrastructure. These efforts form part of a wider push to strengthen Egypt’s position as a regional technology hub.
The country’s National Artificial Intelligence Strategy for 2025–2030 provides a framework for expanding the sector. Its objectives include developing Egypt’s AI ecosystem, improving data infrastructure, encouraging innovation and increasing the use of AI across government and economic activities.
At the same time, the expansion of AI has raised concerns over cybersecurity. According to the report, cyberattacks in Egypt increased by 53 per cent in 2025 amid the growing misuse of AI tools. The development highlights the security challenges that can accompany wider access to increasingly sophisticated digital technologies.
Cybersecurity is particularly relevant to financial institutions because central banks and banking systems handle sensitive information and support critical economic functions. As a result, discussions on AI adoption are closely linked to questions of data protection, risk management and institutional governance.
Egypt has set a target for AI to contribute 7.7 per cent of gross domestic product by 2030. The country also plans to train 30,000 AI specialists and expand AI-related skills among government employees and the wider population. Public awareness is another part of the planned development of the country’s AI capabilities.
Egypt’s cooperation with African financial institutions has also expanded through digital initiatives. In early August, the Central Bank of Egypt and the Association of African Central Banks launched a digital portal for the African Financial Stability Committee. The initiative is intended to strengthen cooperation among African central banks and support more resilient financial systems.
The Nairobi meetings are addressing several broader challenges facing African central banking alongside the AI agenda. These include strengthening monetary policy frameworks, developing domestic financial markets, identifying alternatives to external financing and creating more integrated pan-African payment systems.
The discussions place AI within a wider debate about the future of African financial systems. For central banks, the technology offers potential tools for analysing information and improving internal processes, while also creating new requirements for oversight, cybersecurity and responsible governance.
The annual meetings are scheduled to conclude with the Association of African Central Banks Assembly of Governors. The assembly will consider decisions concerning the association’s activities, technical committees and working groups, bringing the wider discussions on financial stability, cooperation and technological development to the formal decision-making stage.