Under the existing directives, banks and financial institutions have been instructed to remain vigilant and strengthen monitoring of customers’ accounts to prevent cryptocurrency-related transactions through the formal banking system. The latest instructions will remain in force for one year from the date of issuance of the circular.
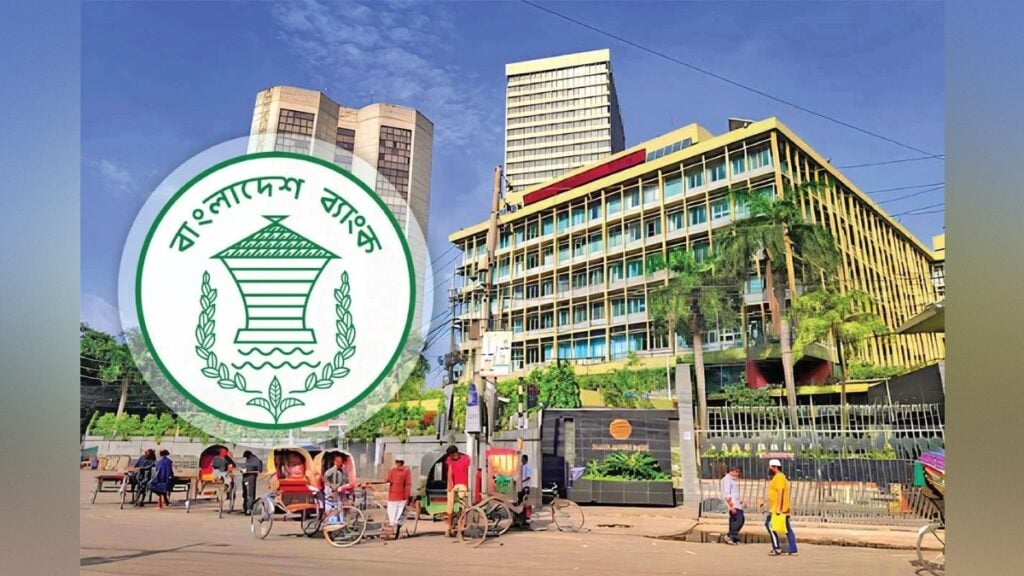
Bangladesh Bank issued the circular on Thursday (29 October), reiterating its position on virtual assets and their use in the country’s financial system.
The latest directive forms part of a broader set of guidelines covering foreign exchange management and related banking operations. These include exchange rate arrangements and reporting requirements, transactions between authorised dealer (AD) banks and Bangladesh Bank, and payments and settlements through the Asian Clearing Union (ACU).
The guidelines also cover foreign currency accounts, limits on banks’ foreign exchange open positions, reconciliation of Nostro accounts, forward transactions and swaps. Provisions relating to hedging against fluctuations in commodity prices in import trade have also been incorporated.
Alongside these areas, the consolidated policy framework explicitly includes restrictions on the exchange, transfer and transaction of virtual assets and virtual currencies. This reinforces the central bank’s position that cryptocurrency-related activities cannot be conducted through authorised financial institutions.
Bangladesh Bank’s restrictions on virtual currencies date back several years. On 15 September 2022, its Foreign Exchange Policy Department issued a circular stating that transactions intended to acquire virtual assets or virtual currencies from Bangladesh, into Bangladesh or within the country were not permitted.
The central bank followed this with another instruction on 12 October 2022, directing banks to strengthen monitoring and take measures to prevent such transactions. Financial institutions were asked to remain alert to attempts to use banking channels for cryptocurrency-related activities.
The latest circular reiterates those earlier instructions and places the restrictions within a consolidated framework governing foreign exchange operations.
Explaining the regulatory position, Bangladesh Bank has stated that virtual currencies are not recognised as legal currency under the Foreign Exchange Regulation Act 1947. They are not backed or guaranteed by any sovereign state, unlike conventional national currencies.
This lack of sovereign backing, combined with substantial price volatility, exposes users and investors to considerable financial risks. Cryptocurrency values can rise or fall sharply within short periods, making investments particularly vulnerable to sudden market movements. Investors may also face difficulties recovering their money if transactions go wrong, as these assets do not carry the same protections as conventional banking products.
Despite the restrictions, interest in cryptocurrency appears to be growing in Bangladesh, particularly through online platforms. Recent international research suggests that the country continues to feature in the global cryptocurrency adoption landscape, even though such transactions are not permitted under the central bank’s existing rules.
According to the 2026 Geography of Cryptocurrency Report, published by international blockchain analytics firm Chainalysis, Bangladesh ranked 56th among 117 countries in grassroots cryptocurrency adoption this year.
The report examined cryptocurrency adoption trends across countries, offering an indication of how extensively digital assets are being used at the grassroots level. Bangladesh’s position suggests that cryptocurrency-related activity remains part of the country’s wider digital financial landscape.
Among neighbouring South Asian countries, India ranked sixth, Pakistan 25th and Sri Lanka 82nd. The rankings highlight differences in the extent of cryptocurrency adoption across the region.
Cryptocurrencies operate through digital networks, often using blockchain technology to record and verify transactions. Their decentralised nature allows transfers to take place without relying on traditional banking intermediaries. However, the same characteristics can create regulatory challenges, particularly when authorities seek to monitor cross-border financial movements and identify the parties involved in transactions.
For Bangladesh, the central bank’s continued restrictions reflect concerns over financial security, foreign exchange management and the risks associated with unregulated digital assets.
The renewed instructions also place responsibility on banks and financial institutions to prevent their services from being used to facilitate cryptocurrency transactions. With online interest in virtual currencies continuing to attract attention, the balance between financial regulation, consumer awareness and emerging digital technologies remains an important issue for the country’s financial sector.