Under the leadership of the Insurance Development and Regulatory Authority (IDRA), a significant turnaround has begun across Bangladesh’s life insurance sector. Over the past month and a half, life insurance companies across the country have successfully disbursed outstanding claims amounting to 639.13 million Taka (63.91 crore Taka).
To rebuild public trust, protect the legitimate rights of policyholders, and eliminate systemic anomalies, IDRA strictly implemented the ‘First In, First Out’ (FIFO) processing rule. This mechanism mandates that long-pending valid claims must be settled strictly in order of seniority, eliminating room for lobbying, favouritism, or administrative delays. Thanks to this zero-tolerance stance and ongoing regulatory reforms, a total of 16,058 general policyholders have received their long-overdue payouts across three consecutive phases.
This intervention comes at a crucial moment for the industry, following years of plummeting public confidence. Much like the country’s banking sector, the insurance arena suffered from widespread allegations of financial mismanagement, operational irregularities, and harassment of clients over the past 17 years. Citizens who invested their hard-earned savings—seeking retirement security or funding for their children’s education—were frequently met with severe delays and excuses when attempting to collect their matured funds.
For more than a decade, policyholders faced persistent obstacles. The most prevalent complaint involved insurance operators offering significantly lower payouts at maturity than specified in the original policy agreements. Companies routinely cited poor financial health or market downturns to justify withholding accumulated bonuses and profits. Marginalised low-income earners, including domestic workers, rickshaw pullers, and small shopkeepers, suffered the brunt of these practices, having sacrificed daily necessities to pay their premiums only to find their mature claims ignored.
Investigations revealed that this breakdown stemmed from unethical corporate governance. Several defaulting firms failed to deposit collected premium payments into dedicated policy accounts. Instead, capital was diverted to acquire real estate for personal gain or laundered abroad. These illicit practices badly tarnished the broader market reputation, penalising compliant companies that operated strictly within legal boundaries.
Following rigorous oversight by IDRA, life insurance providers are now clearing their backlogs. The initial phase on 3 September saw 145.10 million Taka disbursed to 2,549 policyholders. Eleven days later, on 14 September, the second phase delivered 230.35 million Taka to 5,868 clients.
The breakdown of claim settlements across the three phases and key participating entities is outlined below:
| Phase / Entity Name | Date of Disbursement | Total Amount Disbursed (BDT) | Beneficiary Policyholders |
| Phase 1 (Multiple Life Insurers) | 3 September | 145,100,000 | 2,549 |
| Phase 2 (Multiple Life Insurers) | 14 September | 230,350,000 | 5,868 |
| Padma Islami Life Insurance (Phase 3) | 4 October | 90,000,000 | 2,348 |
| Progressive Life Insurance (Phase 3) | 4 October | 67,800,000 | 2,140 |
| Sunlife Insurance (Phase 3) | 4 October | 53,500,000 | 1,573 |
| Homeland Life Insurance (Phase 3) | 4 October | 48,790,000 | 1,381 |
| Sunflower Life Insurance (Phase 3) | 4 October | 300,000 | 165 |
| Baira Life Insurance (Phase 3) | 4 October | 581,892 | 34 |
| Phase 3 Total (6 Selected Insurers) | 4 October | 263,671,892 | 7,641 |
| Grand Total Across All 3 Phases | 3 September – 4 October | 639,121,892 | 16,058 |
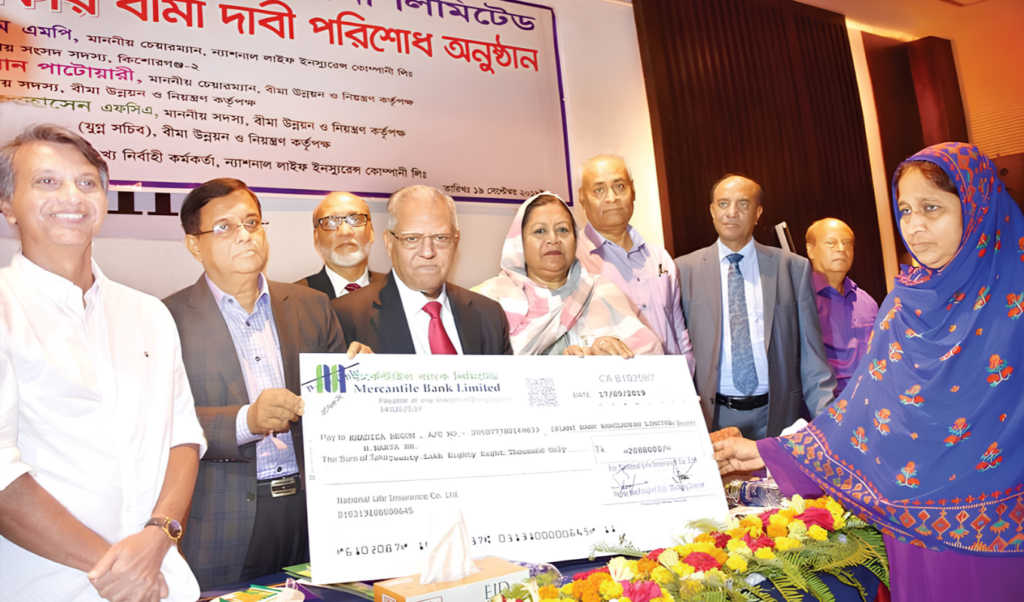
The regulatory push is having an impact beyond Dhaka, with regional branches redirecting resources toward settling claims rather than exclusively chasing new sales. Popular Life Insurance PLC recently held a major distribution event in the Chattogram region, directly handing over claim cheques worth 96.75 million Taka to clients.
During the ceremony, BM Yousuf Ali, Managing Director and CEO of Popular Life Insurance and President of the Bangladesh Insurance Forum, emphasised that the true measure of an insurance company lies in transparent, timely settlements rather than aggressive premium collection.
To ensure these initial gains deliver lasting reform, financial analysts recommend three immediate regulatory steps: introducing mandatory monthly audits of pending claims, establishing a centralised digital tracking system for delayed payouts, and pursuing criminal prosecution against rogue executives who siphoned off policyholder funds, including liquidating diverted assets to repay clients. Restoring complete public trust remains essential if Bangladesh’s insurance sector is to serve as a stable foundation for broader economic growth.