President Mirza Fakhrul Islam Alamgir has urged bank owners and senior bankers to take greater responsibility for restoring public confidence in Bangladesh’s banking sector and rebuilding its reputation.
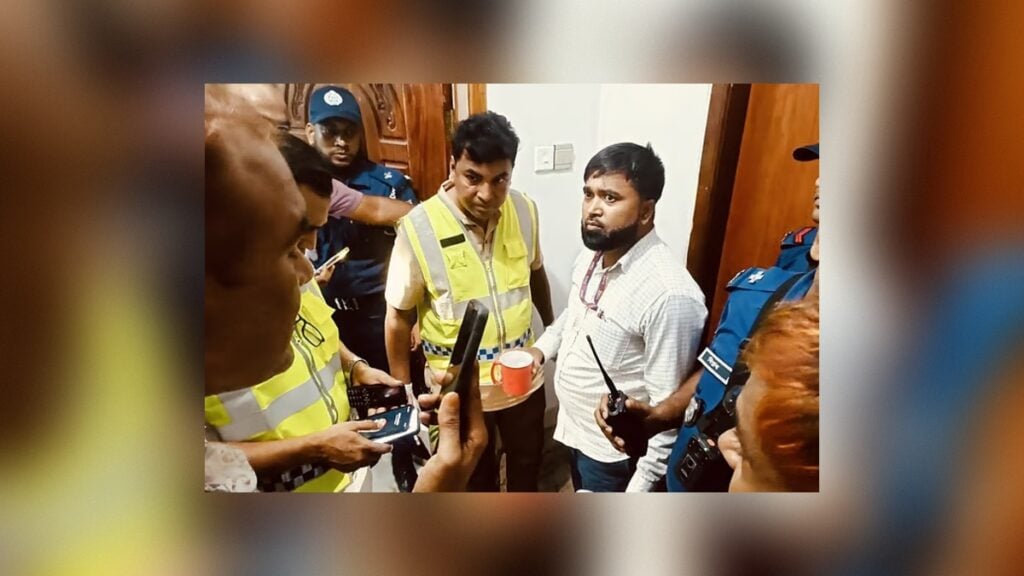
He made the call on Thursday when a delegation of the Bangladesh Association of Banks (BAB), led by its Chairman Abdul Hai Sarker, met him at Bangabhaban in the afternoon. President’s Press Secretary Md Sarwar Alam briefed journalists following the meeting.
The delegation included chairmen, managing directors and chief executive officers of 26 state-owned and private banks, giving the meeting broad representation from across the banking industry.
During the discussion, the President said the country’s people had spent years struggling for democracy and good governance, while large sums of money were allegedly siphoned out of the country through the banking system with the backing of influential quarters.
According to the President, such developments have contributed to making the banking sector extremely fragile. He stressed that bankers and bank owners must now act responsibly to help address weaknesses in both the economy and the financial system.
Restoring the confidence of depositors and ordinary customers, he said, should be a key priority for the sector. Public trust is particularly important for banks because the financial system depends heavily on people and businesses placing their funds with banks and using them for savings, payments, investment and borrowing.
The President also said that the current government was not appointing political figures as directors of banks. He expressed the hope that the approach would contribute to reducing irregularities and strengthening governance within financial institutions.
Focus on CSR and new entrepreneurs
Mirza Fakhrul also called on bank owners to make more effective use of funds allocated for corporate social responsibility (CSR). He suggested that such resources could support technology and engineering education institutions, hospitals and colleges, as well as broader initiatives aimed at social development and public welfare.
He also urged banking leaders to expand access to credit for new and young entrepreneurs. Greater financing for emerging businesses, he said, could help encourage investment in innovative areas, including agro-processing industries.
Access to finance remains an important issue for entrepreneurs, particularly those seeking to establish new businesses or expand into sectors that require investment in technology and production capacity. The President therefore called for greater attention to initiatives that can encourage productive investment.
Bankers raise concerns over default loans
At the meeting, BAB leaders described the banking sector as one of the main driving forces of the national economy. At the same time, they highlighted several problems that they said had weakened the sector over the years.
They said thousands of crores of taka had turned into default loans after powerful groups allegedly siphoned money from banks. The delegation also described the failure to adequately protect depositors’ interests as a humiliating situation for the banking industry.
The issue of default loans has broader implications for banks because a high volume of non-performing loans can affect their ability to recover funds and extend fresh credit. It can also place pressure on the overall health of financial institutions.
The BAB delegation further said that only around 30 per cent of the country’s total financial transactions were conducted through banking channels. They stressed the need to expand the digital economy and promote QR code-based transactions to increase the use of formal financial services.
Calls for wider banking access
The bankers also raised a number of proposals concerning the future development of the sector. These included increasing employment opportunities in banking, expanding bank branches to village-level areas and maintaining the existing rules governing paid-up capital and dividend payments.
They also emphasised the importance of maintaining law and order for the smooth operation of banks and businesses.
The delegation briefed the President on the banking sector’s current problems, challenges and prospects. The discussion covered issues ranging from public confidence and default loans to digital transactions, access to finance and the broader role of banks in supporting economic activity.
The meeting comes at a time when restoring confidence in financial institutions remains closely linked to improving governance, protecting depositors and ensuring that bank financing reaches productive areas of the economy.